
Best Mutual Funds for Conservative Investors
Discover the best mutual funds for conservative investors in India to protect your capital, beat inflation, and build stable, tax-smart wealth as of 2026.

- NV Trends
- 14 min read
- Updated
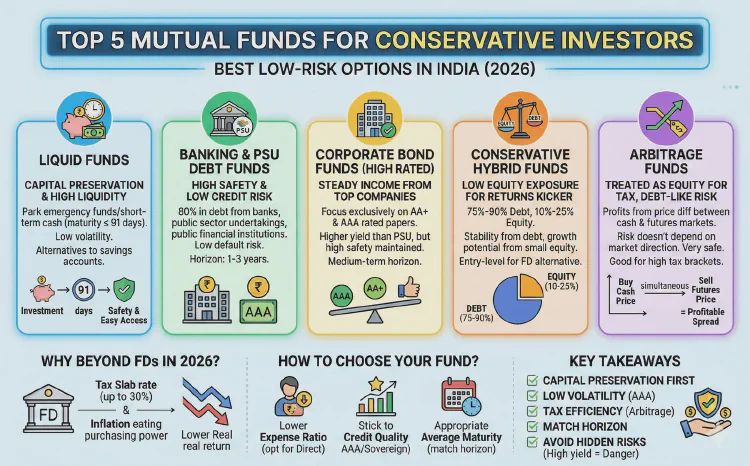
The best mutual funds for conservative investors in India prioritize capital preservation and steady accrual income by allocating primarily to sovereign debt, AAA-rated corporate papers, and low-volatility hybrid or arbitrage instruments designed to outpace inflation.
For decades, Indian households have channeled the majority of their household savings into traditional bank Fixed Deposits (FDs), Post Office schemes, and Public Provident Fund (PPF) accounts. While these options provide guaranteed nominal returns, the financial landscape as of 2026 presents a structural challenge: rising living costs and revised income tax slabs can significantly erode post-tax purchasing power. When bank deposit interest is taxed at marginal slab rates reaching 30% or more, real inflation-adjusted wealth often stagnates or declines.
Conservative investing is not about eliminating risk entirely; it is about taking calculated, minimal risks to ensure your purchasing power increases over time without subjecting your principal to unpredictable market crashes. Modern mutual fund structures offer disciplined risk management, institutional credit oversight, and superior liquidity compared to locked-in physical deposits. By selecting the right categories, low-risk investors can construct resilient portfolios that balance security with consistent wealth generation.
Key takeaways
- Capital Preservation First: Conservative mutual funds restrict their portfolios to sovereign debt, quasi-government debt, and AAA-rated corporate issuers to minimize default risk.
- Smart Asset Allocation: Top conservative allocation mutual funds blend 75% to 90% fixed-income instruments with a small 10% to 25% equity slice to achieve inflation-beating returns without excessive volatility.
- Enhanced Tax Efficiency: Utilizing arbitrage funds and structured Systematic Withdrawal Plans (SWP) allows investors in higher tax brackets to generate regular cash flow with substantially lower tax drag than standard bank FDs.
- Passive Certainty: Conservative index funds tracking government securities (G-Secs) and State Development Loans (SDLs) offer transparent, low-cost options that eliminate fund manager bias.
What Defines a Conservative Fund in India?
A conservative fund is an investment vehicle designed primarily to defend capital while generating regular, predictable income. Unlike aggressive equity schemes that pursue capital appreciation by acquiring high-growth mid-cap or small-cap stocks, conservative portfolios emphasize capital stability, high liquidity, and low portfolio volatility.
Under guidelines established by the Securities and Exchange Board of India (SEBI), mutual funds are strictly categorized by their underlying asset composition. For conservative investors, the mandate is clear: fund managers must deploy the vast majority of assets into fixed-income securities, money market instruments, or market-neutral arbitrage trades.
Risk management in these funds operates across two primary dimensions:
- Credit Risk: The risk that an issuer defaults on principal or interest payments. Conservative funds mitigate this by lending almost exclusively to the Government of India, Public Sector Undertakings (PSUs), and blue-chip corporations bearing ‘AAA’ or ‘AA+’ credit ratings from recognized rating agencies.
- Duration (Interest Rate) Risk: Bond prices move inversely to interest rates. When benchmark rates fluctuate, long-dated bonds experience capital price swings. Conservative portfolios carefully manage Macaulay duration—often keeping portfolio maturities short or holding bonds to maturity—to insulate investors from market volatility.
Best Conservative Asset Allocation Funds: Top 5 Categories to Consider
Asset allocation determines more than 90% of portfolio performance over multi-year horizons. For individuals seeking the best conservative investment funds, spreading capital across distinct, complementary fixed-income and hybrid categories delivers consistent returns while hedging against macroeconomic shifts.
1. Conservative Hybrid Funds: The Top Conservative Allocation Mutual Funds
Conservative hybrid funds represent the traditional definition of conservative asset allocation in the Indian mutual fund industry. Under SEBI mandates, these funds invest between 75% and 90% of their total assets in debt securities, while the remaining 10% to 25% is allocated to domestic equities.
The debt portion functions as a defensive anchor, generating predictable interest accrual from government bonds, treasury bills, and high-grade corporate debentures. Meanwhile, the 10% to 25% equity allocation—typically invested in large-cap, dividend-paying Nifty 50 companies—acts as a performance booster. This equity component allows the fund to outpace retail inflation over a 3- to 5-year investment horizon.
During market downturns, the fund manager rebalances by booking profits or deploying debt accruals into undervalued blue chips, providing an automated asset allocation mechanism that individual savers rarely execute on their own.
2. Arbitrage Funds: Low-Risk Conservative Investment Funds with Equity Taxation
Arbitrage funds are uniquely suited for conservative savers in higher tax brackets. While technically classified as equity-oriented funds under Indian tax law because they maintain an average equity exposure above 65%, their risk profile closely resembles that of a liquid or ultra-short duration debt fund.
Fund managers do not speculate on whether the stock market will rise or fall. Instead, they exploit temporary pricing discrepancies between the cash (spot) market and the derivatives (futures) market. For instance, if a stock trades at Rs. 1,000 in the cash market and its one-month futures contract trades at Rs. 1,007, the manager buys the stock in the cash segment and simultaneously sells the futures contract.
Because both positions converge at contract expiry, the profit (the Rs. 7 spread, known as the cost-of-carry) is locked in regardless of subsequent market movements. The remaining portfolio (up to 35%) is parked in liquid money market instruments. Because they qualify for equity taxation, long-term gains enjoy favorable statutory rates, making arbitrage funds an exceptional substitute for short-term fixed deposits.
3. Banking and PSU Debt Funds: High Sovereign and Quasi-Government Security
For risk-averse individuals who prefer pure debt exposure with zero equity exposure, Banking and PSU debt funds are an outstanding choice. SEBI mandates that these schemes invest at least 80% of their total assets in debt papers issued by commercial banks, Public Sector Undertakings, public financial institutions, and municipal corporations.
These entities are either majority-owned by the Government of India or represent systemically important financial institutions that are considered “too big to fail.” Consequently, the credit default risk associated with these issuers is negligible. Banking and PSU funds generally maintain a moderate duration profile (often 1.5 to 3.5 years), allowing investors to benefit from stable yield-to-maturity (YTM) without taking on speculative corporate credit risk. To review how these compare against other fixed-income schemes, read our detailed analysis of the best debt mutual funds for safe returns.
4. High-Grade Corporate Bond Funds: Accrual Yield Without Compromising Safety
Corporate bond funds provide an avenue for conservative investors to earn a slight yield pickup over sovereign debt while maintaining institutional safety standards. By regulatory mandate, corporate bond funds must invest at least 80% of their total assets in highest-rated corporate debt papers—specifically those rated ‘AAA’ or ‘AA+’.
Fund managers construct these portfolios by investing in debentures issued by blue-chip private sector conglomerates, top housing finance companies, and leading infrastructure entities. Because corporate bonds carry a modest liquidity and credit spread over sovereign gilts, their yields are typically 50 to 120 basis points higher than comparable government securities. For an investor with a 2- to 3-year horizon, sticking strictly to AAA-oriented corporate bond funds avoids the dangerous pitfall of chasing yields in low-rated credit opportunity schemes.
5. Conservative Index Funds and Target Maturity Funds
Passive investing is no longer confined to equity indices. Over recent years, the Indian market has seen substantial growth in debt-oriented conservative index funds and Target Maturity Funds (TMFs) tracking indices constructed by the National Stock Exchange (NSE) or CRISIL.
A conservative index fund typically tracks a sovereign basket, such as a 5-Year G-Sec Index or a State Development Loan (SDL) index. Target Maturity Funds have a predefined maturity year (for example, target maturity 2028 or 2030). These funds hold government-backed securities to maturity, meaning their duration risk steadily rolls down as the maturity date nears. Investors who hold the fund until its target maturity date largely eliminate interest rate volatility and can forecast their annualized yield with high precision. Furthermore, passive index funds feature rock-bottom expense ratios, preserving net returns for conservative investors.
Comparison of the Best Conservative Investment Funds in India
Selecting among conservative funds requires matching your holding period, liquidity needs, and tax situation with the fund’s underlying asset mandate. The table below compares the five primary categories available to Indian investors as of 2026:
| Fund Category | Typical Asset Allocation | Average Credit Profile | Recommended Horizon | Tax Classification (India, as of 2026) | Primary Benefit |
|---|---|---|---|---|---|
| Conservative Hybrid Funds | 75%–90% Debt, 10%–25% Equity | AAA / Sovereign / Blue-Chip Equity | 3 to 5 Years | Debt taxation (taxed at slab rate) | Generates inflation-beating returns with equity kicker |
| Arbitrage Funds | 65%–80% Hedged Equity, 20%–35% Debt | Fully hedged equity + AAA money market | 6 Months to 1 Year | Equity taxation (LTCG 12.5% above Rs. 1.25L; STCG 20%) | Superior post-tax yield compared to short-term FDs |
| Banking & PSU Debt Funds | Min 80% in Banks, PSUs, and PFIs | Sovereign / AAA quasi-government | 1 to 3 Years | Debt taxation (taxed at slab rate) | Near-zero default risk; high institutional safety |
| Corporate Bond Funds | Min 80% in AAA / AA+ rated debt | AAA corporate debentures | 2 to 4 Years | Debt taxation (taxed at slab rate) | Yield pickup over sovereign bonds without junk credit |
| Conservative Index Funds (TMFs) | 95%–100% G-Secs / SDLs / AAA PSUs | 100% Sovereign / AAA | Matches index maturity date | Debt taxation (taxed at slab rate) | Roll-down duration risk, low expense ratio, predictable yield |
Conservative Investment Companies: Examples and Selection Criteria in India
When deploying capital into low-volatility fixed-income products, the institutional pedigree of the Asset Management Company (AMC) is just as critical as the fund category. Conservative investment companies are asset managers recognized for stringent risk controls, independent credit appraisal committees, and conservative liquidity buffers.
Prominent conservative investment companies examples in the Indian asset management industry include:
- SBI Mutual Fund: Backed by India’s largest public lender, SBI Mutual Fund manages massive debt assets with a heavy institutional bias toward sovereign gilts and top-tier PSU papers.
- HDFC Mutual Fund: Known for rigorous internal credit assessments, HDFC AMC has historically prioritized liquidity and portfolio quality over chasing incremental yield in lower-rated credit.
- ICICI Prudential Mutual Fund: A pioneer in hybrid strategies and dynamic duration management, offering extensive offerings across conservative hybrid, banking & PSU, and target maturity index structures.
- Kotak Mahindra Mutual Fund: Widely respected for disciplined treasury operations, strong liquidity management in money market funds, and clear separation of credit risk from accrual mandates.
- Aditya Birla Sun Life Mutual Fund: Manages well-established conservative allocation funds and maintains transparent portfolio disclosures aligned with Association of Mutual Funds in India (AMFI) reporting standards.
When evaluating conservative investment companies, check whether the AMC has ever experienced a significant credit write-off or delayed redemption in its debt schemes during past liquidity squeezes. Conservative fund houses typically reject high-yielding promoter funding papers and structured debt obligations that carry hidden liquidity traps.
How Conservative Index Funds Differ from Active Conservative Allocation Funds
Investors comparing passive conservative index funds with active conservative allocation mutual funds must weigh cost against flexibility.
A conservative index fund operates on a rules-based index methodology. For example, a target maturity G-Sec index fund simply mirrors a basket of Central and State government securities. The passive fund manager cannot alter credit selection, take cash calls, or switch into corporate paper. The advantages are total portfolio transparency, zero credit risk (when tracking sovereign indices), and rock-bottom expense ratios—often between 0.05% and 0.20% for Direct plans.
In contrast, active conservative allocation funds (such as Conservative Hybrid schemes) empower the fund manager to actively alter duration, adjust equity sector exposure, and rotate between sovereign bonds and corporate debentures based on macroeconomic monetary policy signals from the Reserve Bank of India (RBI). While active management incurs higher expense ratios (frequently 0.50% to 1.10% for Direct plans), the dynamic equity allocation provides downside buffering and superior inflation resistance over long periods.
Investors who want pure, predictable fixed-income accrual generally lean toward conservative index funds, whereas those seeking a complete all-in-one replacement for traditional long-term savings often select conservative hybrid funds. To maintain a clear view of your portfolio’s health, review our practical guide on how to track your mutual fund performance.
Strategic Portfolio Construction: How to Select Conservative Funds to Invest In
Building a stable portfolio requires organizing your capital into distinct functional tiers based on your timeline and cash flow requirements. Rather than picking a single scheme, conservative investors should structure their assets across three distinct buckets:
[Conservative Investment Portfolio]
  │
  ├── 1. Emergency & Immediate Liquidity (0-1 Year Horizon)
  │     └── Allocations: Liquid Funds & Arbitrage Funds (High liquidity, zero exit penalty after days)
  │
  ├── 2. Core Capital Preservation (1-3 Year Horizon)
  │     └── Allocations: Banking & PSU Debt + AAA Corporate Bond Funds (Accrual income, high credit safety)
  │
  └── 3. Inflation Protection & Cash Flow (3-5+ Year Horizon)
        └── Allocations: Conservative Hybrid Funds & Target Maturity Index Funds (Equity kicker, SWP capability)
Leveraging Systematic Withdrawal Plans (SWP) for Monthly Cash Flow
For retirees and income-seeking investors, holding conservative funds and setting up a Systematic Withdrawal Plan (SWP) is vastly superior to living off bank FD interest.
When you withdraw money via an SWP, your redemption consists of two parts: a return of your original capital and a capital gain component. Income tax applies exclusively to the capital gain portion, not to the principal being returned. In contrast, bank FD interest is fully taxable in the year it accrues, regardless of whether you withdraw it or reinvest it. Furthermore, mutual fund units continue compounding undisturbed until the exact date of redemption, maximizing tax deferral over your retirement timeline.
Mistakes Conservative Investors Must Avoid
Even in low-volatility categories, poor execution can undermine your financial security. Guard against these frequent mistakes:
- Chasing Yields in Credit Risk Funds: If a debt fund is yielding 1.5% to 2.5% more than its peers, it is almost certainly holding lower-rated (AA or BBB) instruments. A single credit default can wipe out several years of interest accrual. Conservative investors should never compromise credit quality for incremental yield.
- Ignoring Expense Ratios in Low-Yielding Categories: When expected fixed-income yields hover around 6.5% to 7.5%, paying a 1.2% expense ratio in a ‘Regular’ plan forfeits roughly 15% to 20% of your total return to distributor commissions. Always opt for ‘Direct’ plans through AMC portals or SEBI-registered execution platforms.
- Mismatched Investment Horizons: Investing in a 5-year G-Sec fund when you need your capital in 6 months exposes you to mark-to-market interest rate fluctuations. Always align the fund’s average maturity with your personal withdrawal horizon.
- Treating Conservative as “Zero Volatility”: Conservative hybrid funds contain up to 25% equities. During deep equity corrections, the Net Asset Value (NAV) of a conservative hybrid fund will decline temporarily. Investors must understand this trade-off: short-term NAV movements are the necessary price paid for long-term purchasing power defense. For more insight into portfolio pitfalls, explore our guide on how to avoid common investment mistakes.
FAQ
What are the best conservative asset allocation funds for Indian investors as of 2026?
Conservative hybrid funds represent the benchmark for conservative asset allocation in India. By combining 75% to 90% high-quality debt with 10% to 25% large-cap equity, these funds provide regular accrual income while using the equity portion to comfortably beat inflation over 3- to 5-year periods.
How does a conservative index fund compare to a conservative hybrid fund?
A conservative index fund is a 100% passive fixed-income fund that tracks sovereign or AAA bond indices (such as Target Maturity G-Sec or SDL funds) with rock-bottom expense ratios and zero equity exposure. In contrast, a conservative hybrid fund is an actively managed vehicle that includes up to 25% equities to deliver higher capital growth potential over the long term.
What are prominent conservative investment companies examples in the Indian market?
Leading asset management companies renowned for conservative fixed-income practices include SBI Mutual Fund, HDFC Mutual Fund, ICICI Prudential Mutual Fund, and Kotak Mahindra Mutual Fund. These institutions maintain strict credit appraisal frameworks, broad liquidity cushions, and an aversion to high-risk structured debt papers.
Why are arbitrage funds considered top conservative investment funds despite holding equities?
Arbitrage funds eliminate market direction risk by simultaneously purchasing shares in the cash market and selling matching futures contracts in the derivatives market. Because the price difference (spread) is locked in at the time of trade, the portfolio generates debt-like returns with near-zero volatility while qualifying for favorable equity tax treatment under Indian law.
How should a retiree choose conservative funds to invest in for monthly income?
A retiree should maintain a 6- to 12-month liquidity buffer in arbitrage or liquid funds, park 2- to 3-year living expenses in a Banking & PSU debt fund, and invest the remaining long-term corpus in a conservative hybrid fund. Monthly income can then be generated tax-efficiently by setting up a Systematic Withdrawal Plan (SWP) on the conservative hybrid fund.
Conclusion
Conservative investing in the Indian market is about protecting your financial independence, not avoiding market participation. By stepping beyond the tax inefficiencies and inflation drag of traditional bank fixed deposits, conservative investors can build durable, tax-advantaged portfolios tailored to their lifestyle requirements.
Whether you choose the equity-hedged tax benefits of an Arbitrage Fund, the institutional safety of a Banking & PSU debt fund, or the inflation-beating capabilities of top conservative allocation mutual funds, the guiding principle remains unchanged: prioritize safety of principal, minimize costs, and match fund maturity to your personal time horizon. By sticking with top-tier conservative investment companies and avoiding the trap of high-yield credit risk, you can achieve peaceful, consistent compounding year after year.
- Tags:
- Mutual Funds
- Conservative Investing
- Debt Funds
- Asset Allocation
- Arbitrage Funds
- Personal Finance